Fixed bearings, not forecasts
We plan around what can be measured: your income needs, your timeline and your tax picture. Markets move. The plan holds.
Wealth management · Spokane, Washington
Northgate Wealth Partners helps pre-retirees and affluent households across the Inland Northwest turn savings into a plan they can steer — retirement income, investments, 401(k) rollovers, tax-efficient withdrawals and estate coordination, drawn together.
Five services · One written plan
Our approach
Retirement planning is usually sold as a prediction problem — a guess about what the next decade will do. We treat it as a planning problem instead.
If your income floor, your investment mix and your tax plan are drawn correctly, the weather matters less than the course you have set. That is the work: establishing what you need, what you own, and in what order it should be used.
We plan around what can be measured: your income needs, your timeline and your tax picture. Markets move. The plan holds.
Before a single investment is discussed, we establish where you stand — what you own, what it costs and what each account is meant to do.
Your plan is a document, not a conversation. We revisit it on a schedule and whenever your circumstances change.
Services
Every engagement is built the same way. Most households begin with retirement income and work outward from there — but the five are drawn together, because decisions in one affect the others.
Building an income floor from your portfolio, Social Security and any pension you have earned — so a paycheck keeps arriving after the salary stops.
A portfolio matched to your time horizon, your need for income and the risk you are actually able to carry — not a model handed to you at a distance.
Consolidating workplace accounts when you change jobs or retire, with an eye on fees, investment options and the tax consequences of the move.
Sequencing withdrawals across taxable, tax-deferred and tax-free accounts so more of what you have saved stays in your hands.
Working alongside your attorney and tax professional so beneficiary designations, account titling and your intentions line up.
Process
The work runs the same way every time. You always know which step you are on and what comes next.
An introductory planning meeting. We gather what you own, what you owe, what you spend and when you would like to stop working.
We draw the plan in writing: income sources, portfolio structure, withdrawal order and the estate pieces that need coordinating.
We handle the implementation — accounts, transfers, rollovers — and work with your CPA and attorney wherever the plan touches theirs.
Scheduled reviews rather than market-driven phone calls. We adjust when your life changes, and we will tell you plainly when nothing needs to change at all.
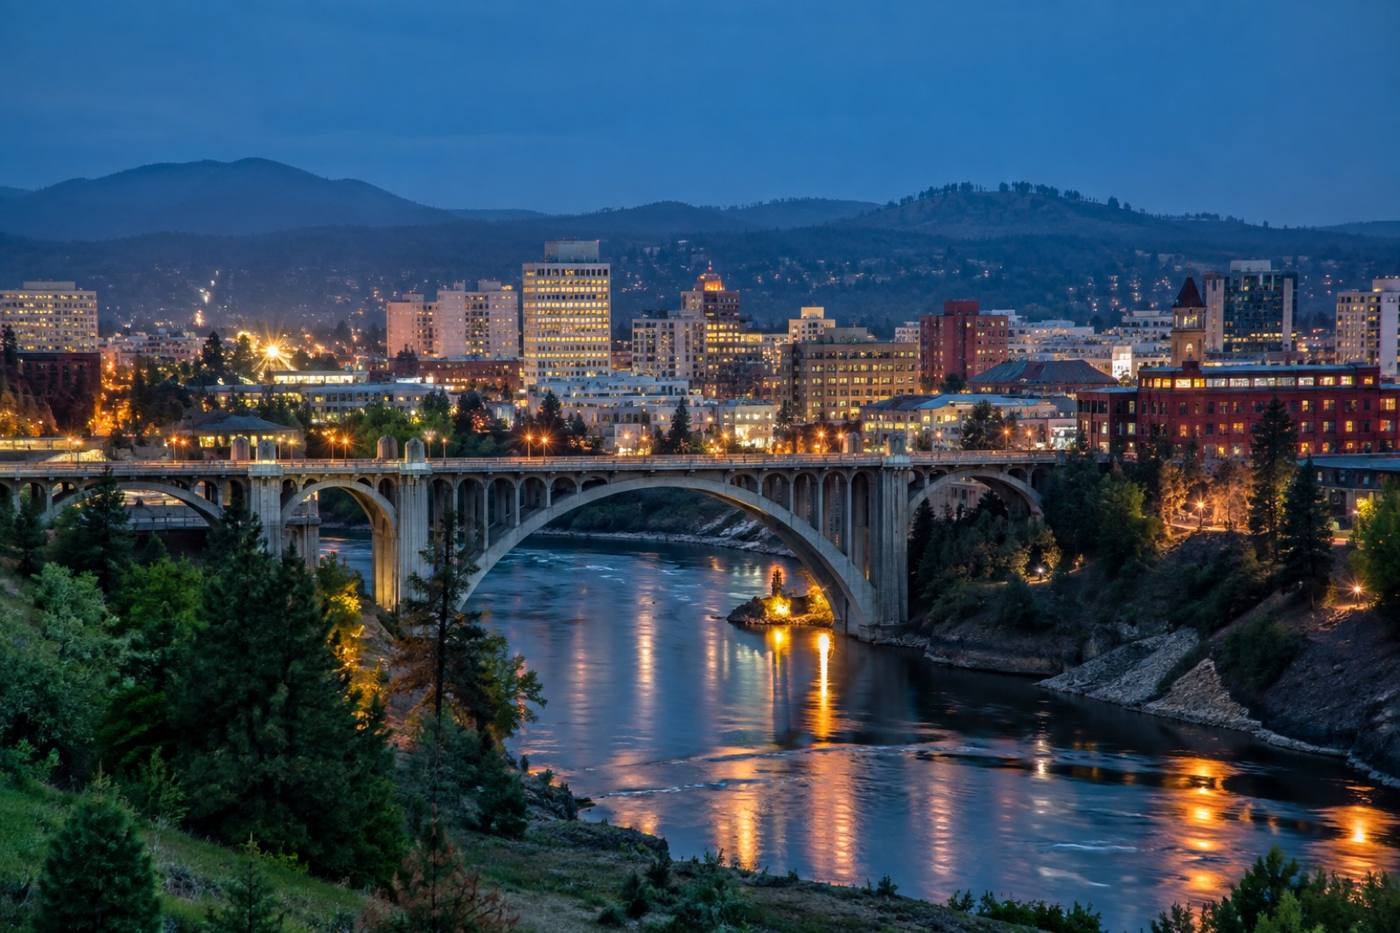
Where we work
Northgate Wealth Partners works with households in Spokane and the surrounding region — people who have spent a career building something and want the next stretch of it to run on their own terms.
A plan is only useful if it survives the weather.
Who we plan for
Households in sight of their last working year, deciding what retirement will actually pay and when it can begin.
Families and individuals with substantial savings, a business interest or property, where tax and estate decisions matter as much as returns.
People holding workplace accounts from one or more employers, waiting on a decision about when and how to move them.
Book a meeting
Tell us where you are and what you would like to work through first. The first conversation is a working session, not a pitch — we look at what you have and describe what we would do with it.
What happens next
Northgate Wealth Partners
Spokane, Washington